A Quality of Earnings report that finds it before the buyer does.
Every adjustment a buyer's accountants discover and you cannot explain comes off your price. We run their analysis first and hand you each finding sourced, documented and ready to defend.
Where You Are in the Deal
Three situations bring people here. What we do is different in each one.
You want to know what a buyer will challenge while you still have time to fix it or explain it.
You are under LOI and need to know whether the earnings you are paying for are actually there.
SBA now requires an independent report on acquisitions of $3M or more, engaged by you rather than the borrower.
What a Quality of Earnings Report Actually Is
An independent analysis of whether a company's reported profit reflects earnings the business can actually repeat. It restates reported EBITDA as a normalized figure, with every adjustment documented, so a buyer, lender or committee can price against a number that holds.
It is a consulting engagement, not an attest engagement. It expresses no opinion on financial statements and provides no assurance. It does not value the business, and it does not replace legal or tax diligence.
What the Report Covers
One report, six schedules, and a call to walk you through the findings before any of it is final.
SBA Now Requires a Quality of Earnings Report
From October 1, on change-of-ownership and expansion acquisitions with a purchase price of $3 million or more. The adjusted earnings figure feeds straight into debt service coverage.
A report commissioned by the borrower or the seller does not satisfy it, and neither does a sell-side report passed along by a broker. We are engaged by the lender, we are not a party to the transaction, and we take no success fee.
Not an Audit, Not a Valuation
A clean audit does not mean earnings are repeatable. A business can be fully compliant and still have a year propped up by one customer about to leave.
| Quality of Earnings | Audit | Valuation | |
|---|---|---|---|
| Answers | Are these earnings repeatable? | Are the statements fairly presented? | What is the business worth? |
| Assurance | None. Findings only, no opinion | Reasonable assurance, formal opinion | A conclusion of value |
| Looks at | Earnings quality, cash, working capital, concentration | Balances, controls, the reporting framework | Income, market and asset approaches |
| Deal use | Priced against directly | Supports lender underwriting | Sets expectations in a market deal |
How the Engagement Works
Four steps. You know where the engagement stands at every stage, and nothing in the final report is a surprise to you.
Most firms describe their reports. Read ours.
A complete report on an anonymized business. Every schedule intact, every adjustment annotated to show what a buyer looks for.
Read the Sample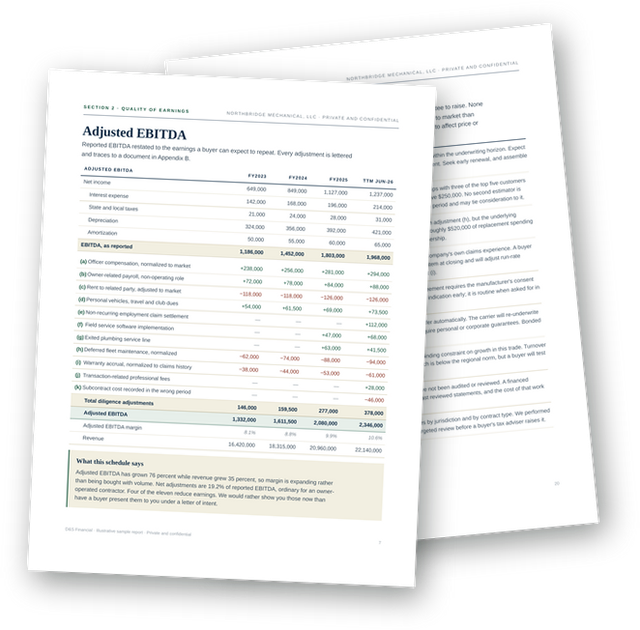
What It Costs
Fixed fee, agreed before we start. The condition of the records moves it more than the size of the business does.
You do not need to name your company to get a quote.
Judge the Work, Not the Logo
We are a small independent practice, and we would rather you evaluate us on what we publish than on a client list. The document request list is on this page. A complete sample report is on this page. The six areas we analyze, in the order we analyze them, are on this page.
Common Questions
The report is yours. We deliver it to you and nobody else, and we walk you through every finding before it is final. A problem found now is one you can fix, explain or price in. The same problem found under LOI is a reduction in your proceeds.
On conventional deals, generally yes, when the work matches buy-side standards and every adjustment traces to a document. On SBA deals above $3 million, no: the lender has to engage it themselves.
No, and this is the most useful time to find out. The condition of the records affects scope and fee more than the size of the business does. Bring us what you have.
From October 1, yes, on change-of-ownership and expansion acquisitions with a purchase price of $3 million or more. It must be engaged by the lender. Owner buyouts, ESOP and cooperative conversions are exempt.
No. Many sellers share it because it shortens diligence and signals preparation, some share parts, some keep it entirely. That is your call and we will talk through the trade-offs.
A short call up front, a document handoff, and typically two to four hours of questions across the engagement, mostly by email.
Get a Quote
Tell us roughly what you are working with. You do not need to name your company. What you send stays confidential, and we reply within one business day.
Confidentiality
Everything you send us stays between us. We do not share inquiries with brokers, buyers or lenders, we do not add you to a mailing list, and we will not contact your company, your staff or your advisors.
We will sign your NDA before any documents change hands, or send you ours.
Rather Not Use a Form?
Call us directly. If you would rather write, use the form: you can send from any address you like, and we will answer the same way.
Independent Quality of Earnings reports and financial due diligence for Main Street through middle market transactions, nationwide.
LinkedInSBA now requires a Quality of Earnings report on acquisitions of $3 million or more.
The requirement takes effect October 1, 2026. The report has to be engaged by the lender, which means a seller's report will not clear it, and the adjusted earnings figure feeds directly into debt service coverage.
Does This Apply to Your Deal?
One detail worth checking before you assume you are under the line: owner-occupied commercial real estate carried at appraised value comes out of the purchase price for this calculation. A deal that looks like $3.4 million with the building in it may sit below the threshold without it.
The report has to be engaged by the lender.
This is the part that catches deals out. A Quality of Earnings report commissioned by the borrower or by the seller does not satisfy the requirement, and neither does a sell-side report handed over by a broker, however good the underlying work is.
If a borrower arrives at the closing table holding a report they paid for themselves, the file still needs an independent one. That is a second engagement and a second fee, landing on a clock that is usually already tight.
What the Report Has to Cover
Four procedures the SOP calls for, and what each one is actually testing.
What It Changes, Depending on Where You Sit
If You Are a Lender
You need a panel of independent providers you can engage directly, with turnaround you can plan a closing around. The adjusted earnings figure lands in your debt service coverage, so the schedules behind it have to hold up in credit review.
If You Are Buying
Budget for it and build it into the timeline early. Your own diligence still has value, but it does not substitute for the lender's report, and discovering that late is how a closing date slips.
If You Are a Broker or Advisor
Listings above $3 million now carry a diligence step you can anticipate. Sellers whose books are clean before going to market will clear it faster, which is a reason to prepare earlier rather than later.
How a Lender Engagement Runs
Four steps. We give you a delivery date at the start and tell you immediately if the borrower’s records change it, so the report is never the thing holding up a closing without warning.
Lenders: we are taking engagements now.
Independent, engaged by you, fixed fee quoted before we start. Send us the deal size and the state of the borrower's records and we will come back with a fee and a date.
As of October 1, 2026, yes, on change-of-ownership and expansion acquisitions with a purchase price of $3 million or more. Below that threshold it is not required, though lenders may still ask for one.
Who bears the cost and who engages the firm are two different questions. The engagement has to run through the lender for the report to count. Talk to your lender about how the fee is handled on their files.
Not for this requirement. A report prepared for the seller or the borrower does not satisfy it, even when the work is sound. It is still useful, and it usually makes the lender's engagement faster because the records are already organized.
On purchase price, before buyer equity, seller notes or other financing is applied, with owner-occupied real estate carried at appraised value excluded from the figure.
We commit to a delivery date on the scoping call and hold it. The condition of the borrower's records affects that date more than the size of the business does.
No requirement, but the same analysis still tells a credit officer whether the earnings are real. Plenty of lenders will keep asking for one on smaller files.
Independent Quality of Earnings reports and financial due diligence for Main Street through middle market transactions, nationwide.
LinkedInRead a complete Quality of Earnings report.
Most firms describe their reports. This is ours, in full, on an anonymized business. Every schedule intact, every adjustment annotated to show what a buyer looks for in it.
What You Are Looking At
A real engagement, with the company, people, locations and figures changed so the business cannot be identified. The structure, the procedures and the way findings are written up are exactly what you would receive.
[D&S TO SUPPLY: the anonymized report. Contents below reflect the structure agreed on the home page.]
An Annotated Page from the Schedule
The notes in green are what we add for you. They are not in a standard schedule, and they are the difference between a number and an argument you can win.
Want the Whole Thing as a PDF?
Email address only. No name, no company, no phone. We will not add you to anything, and we will not follow up unless you ask us to.
Seen Enough?
Tell us roughly what you are working with and we will come back with a fee and a date. You do not need to name your company.
Independent Quality of Earnings reports and financial due diligence for Main Street through middle market transactions, nationwide.
LinkedInPrivacy Policy
Last updated [DATE]
D&S Financial provides Quality of Earnings and financial due diligence services. This policy explains what information we collect through this website and in the course of an engagement, and what we do with it.
What We Collect
From this website, we collect only what you send us. If you complete the enquiry form, that is your name, email address, and the optional details you choose to provide about the transaction. We do not ask for your company name, and you do not need to give it to receive a fee quote.
We also collect standard analytics about how the site is used, including pages viewed and how you arrived. [CONFIRM: analytics platform and whether a consent banner is required for your traffic.]
How We Use It
To reply to your enquiry, scope an engagement and quote a fee. We do not add enquiries to a marketing list, and we do not send newsletters or promotional email.
Who We Share It With
We do not share enquiries with brokers, buyers, lenders, sellers or anyone else. We do not sell personal information. We will not contact your company, your staff or your advisors about an enquiry.
We use service providers for email, file transfer and analytics, who process information on our behalf and under contract. [LIST PROVIDERS.]
Engagement Materials
Documents you provide during an engagement, including financial statements, tax returns, bank statements and payroll records, are handled under the terms of the engagement letter and any non-disclosure agreement in place. We will sign your NDA before documents change hands, or provide ours.
Where an engagement is commissioned by a lender, the report and supporting schedules are delivered to that lender. Where an engagement is commissioned by you, the report is delivered to you, and we do not distribute it to any other party unless you direct us to.
Retention and Security
We retain engagement records for [PERIOD], consistent with professional and insurance requirements, and enquiry records for [PERIOD]. Files are held on [SYSTEMS] with access limited to personnel working on the engagement.
Your Rights
You can ask what information we hold about you, ask us to correct it, or ask us to delete it, subject to records we are required to retain. [COUNSEL TO ADD: state-specific disclosures, including any California, Colorado, Connecticut, Texas or Virginia requirements that apply given a national client base.]
Contacting Us
Write to hello@dandsfinancial.com or [POSTAL ADDRESS].
Independent Quality of Earnings reports and financial due diligence for Main Street through middle market transactions, nationwide.
LinkedInTerms of Service
Last updated [DATE]
These terms govern your use of dandsfinancial.com. They do not govern any engagement, which is set out separately in an engagement letter.
Use of This Site
You may read, print and share this site for your own business purposes. You may not scrape it, republish it commercially, or present its content as your own.
Not Advice
Everything on this site is general information. It is not accounting, tax, legal, lending or investment advice, and reading it does not create a client relationship. Do not act on it without advice specific to your situation.
Nature of Our Services
A Quality of Earnings engagement is a non-attest consulting service. It expresses no opinion on financial statements and provides no assurance. It is not an audit, a review, a compilation or a valuation, and it does not substitute for legal or tax diligence.
SBA Information
Pages describing SBA requirements summarize our reading of SBA SOP 50 10 8.1 as at the date shown. We are not affiliated with, endorsed by or acting on behalf of the U.S. Small Business Administration. Requirements change and are applied by individual lenders. Confirm the current requirements with your lender and the current SOP before relying on anything here.
Engagements
No engagement exists until both parties sign an engagement letter. Fees, scope, deliverables, timing and confidentiality are governed by that letter, which takes precedence over anything on this site, including any fee ranges shown.
Fee ranges published here are indicative. The fee for any engagement is the one quoted and agreed in writing.
Content Ownership
Text, layout, schedules and sample materials on this site belong to [LEGAL ENTITY NAME]. A sample report is provided for illustration on an anonymized basis and may not be reused as a template or represented as work performed for you.
Limitation of Liability
[COUNSEL TO DRAFT. Cover reliance on site content, third-party links, availability, and the cap and carve-outs that align with the engagement letter and the professional liability policy.]
Governing Law
These terms are governed by the laws of [STATE], without regard to conflict of laws principles. [COUNSEL TO CONFIRM venue and any dispute resolution clause.]
Changes
We may update these terms. The date at the top of this page shows when they last changed.
Independent Quality of Earnings reports and financial due diligence for Main Street through middle market transactions, nationwide.
LinkedIn